Tokenized Deposits vs Stablecoins: How Digital Bank Money Differs
Tokenized deposits and stablecoins both move on programmable ledgers, but their issuers, legal claims, settlement, access, and risks differ.

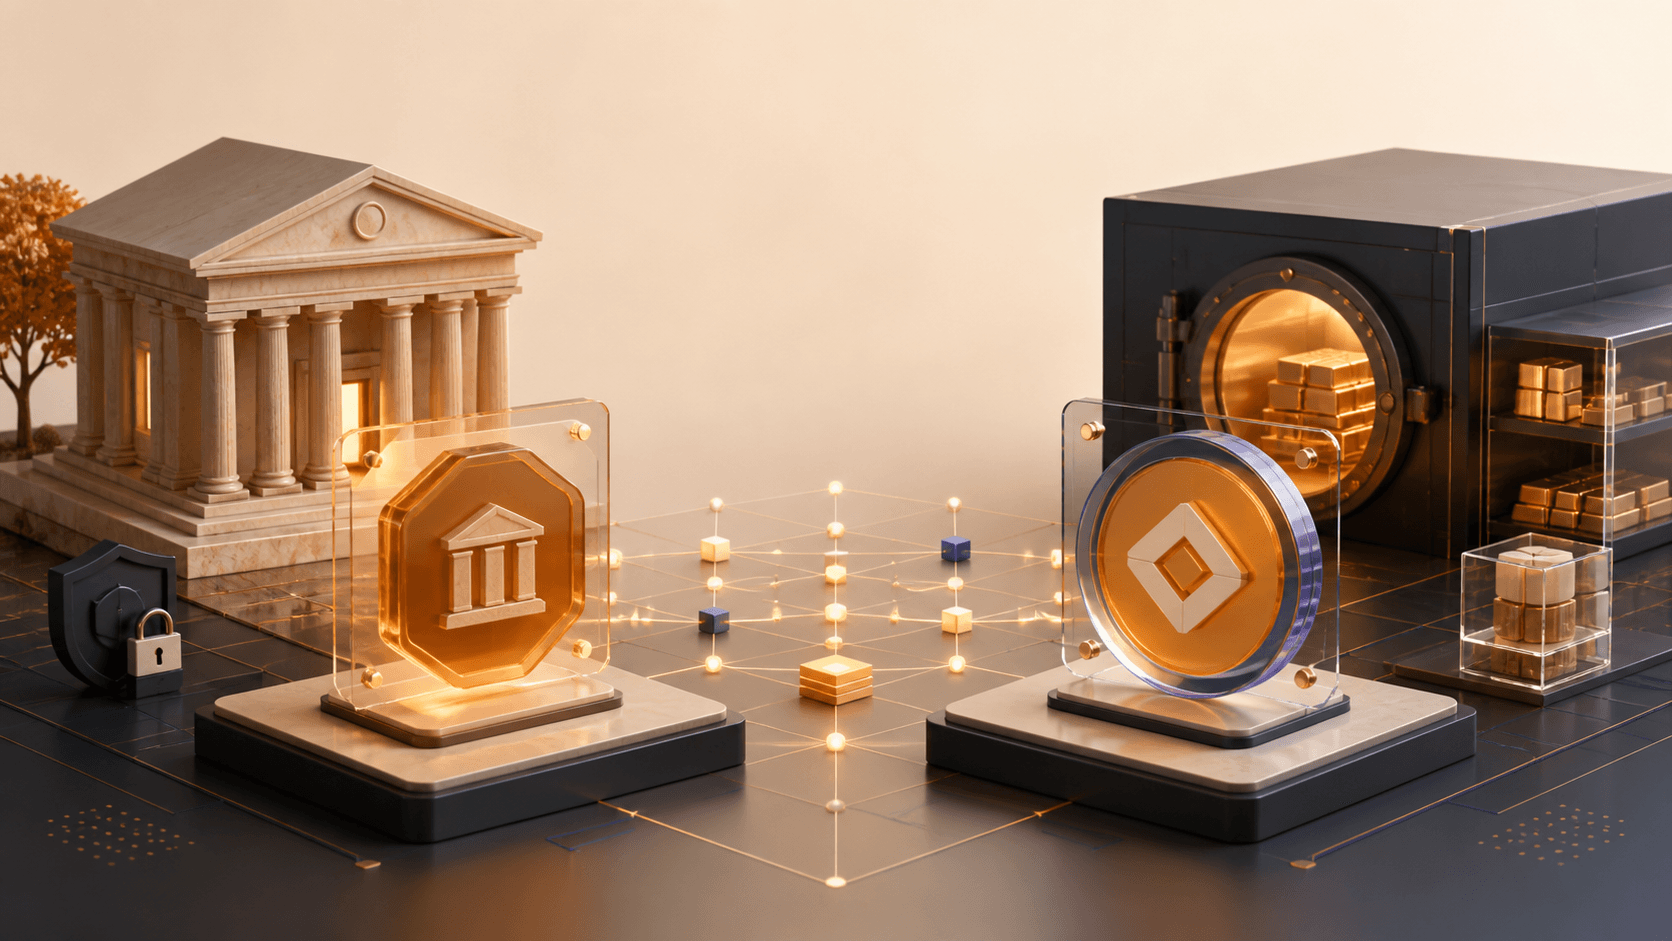
Two digital dollars can look nearly identical in a wallet and still represent different legal and financial relationships. That is the practical puzzle behind tokenized deposits vs stablecoins. Both can move on programmable ledgers, but one is generally a claim on a bank deposit while the other is a token issued against a reserve arrangement. This distinction belongs inside the wider world of real-world asset tokenization, because the payment leg matters whenever an on-chain asset changes hands.
This guide compares the instruments without assuming that one design wins every use case. Terminology and regulation are still evolving, and many tokenized-deposit projects remain pilots or wholesale systems rather than products available to ordinary wallet users.
Not financial advice (NFA). Neither a bank-branded token nor a fiat-pegged token is automatically risk-free. Check the issuer, legal claim, redemption terms, network, jurisdiction, and applicable protections. Do your own research (DYOR).
What Are We Comparing?
A tokenized deposit is a digital representation of commercial bank money on a programmable ledger. The holder's claim is generally a deposit liability of the issuing bank. The exact design matters: some systems update accounts within one bank, while others use transferable tokens and arrangements among multiple banks.
A fiat-referenced stablecoin is a crypto token designed to maintain a stable value relative to a currency, commonly by holding cash and short-dated liquid assets as reserves. The holder usually has a claim defined by the issuer's terms and relevant law, not a deposit account at the reserve-holding bank.
Think of the difference as two ways to carry spending power into a programmable venue. A tokenized deposit is like adding a secure digital access lane to money already recorded on a bank's balance sheet. A reserve-backed stablecoin is more like receiving a transferable claim from a separate issuer that keeps backing assets elsewhere. The interfaces may feel alike; the plumbing is not.
The Bank of England's prudential guidance uses a similar distinction: tokenized deposits are deposit claims represented on programmable ledgers, while fiat-backed stablecoins are digital assets intended to maintain value through backing assets.
Tokenized Deposits vs Stablecoins at a Glance
| Question | Tokenized deposit | Fiat-backed stablecoin |
|---|---|---|
| Who issues it? | A regulated deposit-taking bank | A stablecoin issuer under the applicable framework |
| What is the claim? | Generally a liability of the issuing bank | A claim or redemption right governed by issuer terms and law |
| What backs it? | The bank's balance sheet and prudential framework | Segregated or designated reserve assets, depending on the regime |
| How does it settle? | Design-dependent; interbank obligations can ultimately settle in central bank money | Transfer of the token on its supported ledger; reserve redemption is a separate process |
| Where can it circulate? | Often permissioned and limited to approved participants | Frequently broad on public blockchains, subject to issuer controls and law |
| Can it deviate from par? | Non-bearer designs aim to preserve deposit money at par; transferable designs can add complexity | Secondary-market prices can move above or below the reference value |
| Main risks | Bank credit, operational, interoperability, legal, and access risk | Depeg, reserve, issuer, redemption, smart-contract, and network risk |
| Typical use today | Bank pilots and wholesale settlement experiments | Crypto trading, transfers, payments, and DeFi liquidity |
This table describes common structures, not universal rules. A product's legal documents are more important than its label.
How the Money Moves
Tokenized deposit flow
Imagine a corporate client moving a tokenized deposit from Bank A's environment to a supplier connected to Bank B. The visible token transfer is only part of the job. The banks also need rules for identity, compliance, messaging, finality, and the settlement of obligations between them. Central bank reserves can provide the final settlement anchor.
This is why much of the current work focuses on shared or interoperable infrastructure. The BIS describes tokenization as a way to combine messaging, reconciliation, and settlement, and its 2026 work on the next-generation monetary system reports that the Project Agorá prototype demonstrated atomic cross-border settlement after required validation and balance-locking steps. A prototype is evidence of feasibility, not proof that a global production network is ready.
Stablecoin flow
With a stablecoin, an eligible customer typically sends money to an issuer or authorized intermediary, the issuer mints tokens, and those tokens circulate on supported networks. A holder can transfer them without each recipient opening an account at the issuer's reserve bank. Redemption reverses the process, subject to eligibility, fees, timing, limits, and the issuer's terms.
That portability helped stablecoins become common settlement assets in crypto markets and DeFi. It also creates a separate market price. If demand, liquidity, reserve confidence, or redemption access changes, the token may trade away from par even when it is designed to be redeemable at par.
The Key Difference: The Claim Behind the Token
The most useful due-diligence question is not “Which blockchain does it use?” It is “Who owes me what if I hold this token?”
For a tokenized deposit, the answer is usually the issuing bank, under a deposit relationship. Whether deposit insurance or another protection applies depends on the holder, product, jurisdiction, and structure; tokenization alone does not create coverage.
For a stablecoin, the answer depends on the issuer's redemption promise and legal framework. Reserve assets may be held with banks or custodians, but owning the stablecoin normally does not make the holder a direct depositor at those institutions. Insolvency treatment and access to reserves can therefore differ from an ordinary bank deposit.
The BIS comparison of stablecoins and tokenized deposits frames another difference around the “singleness of money”: bank deposits that settle through central bank money are designed to exchange at par, while bearer-like private tokens can develop relative market prices. The BIS is making an institutional-policy argument, so treat it as an authoritative perspective rather than a guarantee about every implementation.
Where Each Design May Fit
Tokenized deposits: regulated financial workflows
Tokenized deposits may fit situations where participants already have bank relationships and need programmable settlement: wholesale payments, trade finance, tokenized securities, or delivery-versus-payment. A smart contract can make the asset and payment legs conditional, reducing the risk that one side delivers while the other does not.
The trade-off is access. Permissioned networks, onboarding, cross-bank coordination, and jurisdiction-specific rules can make these systems less open than public-blockchain stablecoins.
Stablecoins: portable on-chain liquidity
Stablecoins fit environments where broad transferability and existing blockchain liquidity matter. They can move between wallets, exchanges, and applications on a supported network, although issuers may retain freeze or blacklist capabilities. Our stablecoin guide explains backing models and depeg risk in more detail.
The trade-off is a layered trust stack: issuer, reserves, custodian, redemption process, smart contract, bridge if used, and the underlying blockchain. Convenience does not remove those dependencies.
Risks That the “Digital Cash” Label Hides
Issuer and credit risk. A tokenized deposit remains exposure to a bank, while a stablecoin depends on its issuer and reserve structure. Regulation can reduce risk; it cannot erase it.
Redemption and liquidity risk. Par redemption may be limited to verified customers, minimum amounts, business processes, or certain jurisdictions. Everyone else may depend on a secondary market.
Smart-contract and network risk. Bugs, key compromise, congestion, chain reorganizations, or governance failures can interrupt transfers. Moving a token through a bridge adds another contract and operator layer.
Legal uncertainty. The token's property status, insolvency treatment, settlement finality, and consumer protections may differ across jurisdictions. A familiar product name does not harmonize the law.
Interoperability and fragmentation. Bank tokens can become isolated silos. Stablecoins can fragment liquidity across issuers and chains. Bridges and wrappers may reconnect those islands, but they add new failure points.
Privacy and control. Permissioned bank systems may embed identity and compliance rules. Public-ledger stablecoins may expose transaction histories while still allowing issuer controls. Neither architecture guarantees privacy or censorship resistance.
The ECB's 2026 payments strategy says tokenized deposits could provide many functions associated with stablecoins, but also notes that governance and transferability need development. That cautious framing is useful: production readiness should be verified, not assumed.
A Practical Due-Diligence Checklist
Before treating any token as cash-like, verify:
- Issuer: Which legal entity owes the obligation?
- Claim: Is it a deposit, e-money claim, security, or contractual redemption right?
- Par access: Who can redeem directly, at what price, and on what timetable?
- Protection: Does deposit insurance, safeguarding, or a reserve segregation rule apply to you?
- Backing: For stablecoins, what assets are held, where, and how often are they disclosed or independently attested?
- Settlement: When is a transfer legally final, and what settles obligations between institutions?
- Technology: Which ledger, contracts, administrators, or bridges can fail or pause?
- Jurisdiction: Are you eligible, and which court or regulator governs the claim?
If the documents do not answer those questions plainly, the token's convenience is not a substitute for clarity.
FAQ
Is a tokenized deposit the same as a CBDC?
No. A tokenized deposit is generally a commercial bank liability. A central bank digital currency is a liability of a central bank. They can share infrastructure or interact in settlement, but the issuer and claim are different.
Is a tokenized deposit safer than a stablecoin?
Not automatically. Bank regulation and possible depositor protections may change the risk profile, but coverage and legal treatment depend on the product and jurisdiction. Tokenized deposits also carry operational, technology, bank-credit, and interoperability risks.
Can tokenized deposits be used in DeFi?
Potentially, if the network, bank, and application rules permit it. Many current designs are permissioned and aimed at wholesale use, so they do not have the open composability associated with public-blockchain stablecoins.
Do tokenized deposits earn interest?
They may, because they can represent deposit claims, but the rate and eligibility depend on the bank and product. Never infer interest, insurance, or redemption rights from the word “deposit” alone.
Will tokenized deposits replace stablecoins?
There is no reliable basis for that prediction. The instruments serve overlapping but different users and infrastructures. Interoperability, regulation, liquidity, and access will shape adoption, and multiple forms may coexist.
Bottom Line
Tokenized deposits and stablecoins both make money usable on programmable rails, but they package trust differently. Tokenized deposits extend a bank liability into a tokenized environment. Stablecoins create a portable token whose value depends on an issuer, reserves, redemption, and market liquidity.
Start with the legal claim, not the interface. Then trace the settlement path, protections, technical dependencies, and exit route. That method is more durable than choosing a side based on a label.
This article is for educational purposes only and is not financial, legal, or investment advice. Rules and product structures vary by jurisdiction and can change. Verify primary documents, consult qualified professionals where appropriate, and do your own research. NFA / DYOR.
Keep learning
Tokenized Treasuries Explained: On-Chain T-Bills, BUIDL, and Real Yield (2026)
Tokenized treasuries let you hold U.S. T-bill yield on-chain, 24/7. How they work, who the big players are, and the layered risks the headline yields skip.
 GOMTU7 min read
Tokenized Stocks Guide 2026: How xStocks, Robinhood & Onchain Equities Work
Tokenized stocks let you hold Apple, Nvidia, and Tesla as blockchain tokens trading 24/7. Learn how xStocks, Robinhood, and Backed work, the four real risks, and where regulation stands in 2026.
GOMTU7 min read
What Are Stablecoins? Types, How They Work, and Real Risks
Understand stablecoins from the ground up — fiat-backed, crypto-backed, algorithmic, and yield-bearing types — plus depeg risks, USDT vs USDC, and how to use them in DeFi.
GOMTU7 min readExplore related topics
Crypto Address Poisoning: How to Verify Wallet Addresses Before You Send
Crypto address poisoning plants a lookalike address in your transaction history. Learn how it works and follow a safer verification checklist.
GOMTU7 min read
Pending Ethereum Transactions: Diagnose, Speed Up, or Cancel Safely
Learn why an Ethereum transaction stays pending, how nonce order and fees affect it, and when speeding up, canceling, or waiting is the safest response.
GOMTU7 min read